Laid Off From Meta and Thinking About Taking 2027 Off? What to Do With RSUs, Severance, and Concentrated META Stock
A friend from Meta called me recently, completely blindsided, asking the same question you may be asking right now:
“I got laid off. I have severance coming. I still own META stock from RSUs. I have some cash. I might take 2027 off before jumping into the next thing. What do I do?”
Here is exactly where I would start.
Before we talk about whether you should sell, hold, or diversify META stock, we need to figure out how long you can live without another paycheck.
Because this is not just a stock decision.
It is a cash flow decision. It is a tax decision. It is a severance decision. It is a health insurance decision. It is a concentrated equity position decision.
And honestly, it may also be a life decision.
If 2026 is the severance year, 2027 may be the planning year.
Key Takeaways
- Your Meta layoff is not just an investment problem. It is a liquidity, tax, benefits, and concentrated equity planning problem.
- Before you make META stock the center of the conversation, you need to understand your cash runway, after-tax severance, health insurance costs, tax reserves, and monthly expenses.
- If your severance package is based on base pay, not total compensation, it may replace less of your real lifestyle than the headline number suggests.
- If your package includes extended COBRA coverage, that may dramatically lower your monthly burn rate and give you more flexibility than you initially thought.
- A meaningful META position after a layoff should be reviewed as a concentrated equity position, not just as shares you happened to receive through compensation.
- If 2026 includes salary, RSU income, PTO payout, and severance, but 2027 may have little or no W-2 income, 2027 may become a strategic planning window.
- This article is educational only and is not a recommendation to buy, sell, or hold META stock.
Why This Question Is Worth Slowing Down For
You worked your tail off at Meta.
You were likely compensated well for that work.
And if a meaningful part of your total compensation came through RSUs, stock options, bonuses, or other equity-linked compensation, your financial life may be more connected to META than you realize.
Then the layoff happens.
Your first reaction is probably:
“Oh no, what am I going to do?”
That is normal.
Getting laid off can feel terrible. It can feel uncertain. It can feel personal.
But once the dust settles, I think you should take a step back and ask a different question:
Could this transition also create an opportunity to plan differently?
Not because a layoff is good news.
It is not.
But if you were a high-income W-2 employee and now you may have a year with little or no income, your tax picture, cash flow picture, and investment picture may look completely different than they did while you were working.
That does not mean you should take a year off just for tax reasons.
But if you are already thinking about taking time off, consulting lightly, starting something new, spending more time with family, or simply recovering from years of working hard in tech, then the planning around that year may matter a lot.
This Is Not One Decision. It Is Several Decisions Happening at Once.
When you ask, “What should I do with my Meta stock now?” I do not think the real question is only about META.
The real question is:
- How is your equity structured?
- What has already vested?
- What has not vested?
- What does your severance package actually cover?
- How much cash do you have right now?
- How much of your normal lifestyle was funded by base pay versus total compensation?
- What will health insurance cost after your Meta benefits change?
- What taxes are already baked into 2026?
- What might 2027 look like if you do not jump right back into another W-2 role?
- How much of your net worth is concentrated in META?
That is why I would not start with a prediction about META stock.
No one can guarantee what any stock will do in the future.
Not me. Not you. Not someone on TV. Not someone on social media. Not the smartest investor in the world.
The better question is:
What job does this money need to do for you now?
Some of your META stock may be long-term investment money.
Some of it may be safety money.
Some of it may be part of a diversification plan.
Some of it may be useful for funding the next chapter of your life.
But we cannot know that until we map the whole situation.
The Better Questions After a Meta Layoff
Before we make your META stock the center of the conversation, I want you to ask:
- How long can I live without another paycheck?
- How much severance will I actually keep after taxes?
- Is my severance based on base pay, or does it meaningfully replace my total compensation?
- Do I have covered COBRA, and if so, for how long?
- How much of my net worth is concentrated in META?
- Which shares have gains, losses, short-term treatment, or long-term treatment?
- Could 2027 be a lower-income planning year?
- Am I making this decision from a plan, or from emotion?
The goal is not to create perfect answers immediately. The goal is to know which questions deserve attention before one emotional stock decision creates pressure.
Start With Liquidity Before You Touch the Stock
The first issue after a layoff is not whether META is a good company.
The first issue is liquidity.
Liquidity is simply access to money when you need it.
After a layoff, liquidity matters because your paycheck may stop, but your life does not.
You may still have:
- Mortgage or rent
- Health insurance
- Childcare
- Taxes
- Debt payments
- Relocation costs
- Family obligations
- Normal spending
- Unexpected expenses
And on top of that, you may lose the day-to-day benefits and perks that made your monthly life feel easier while you were inside Meta.
This is where the math gets real.
If you only have three months of runway, we are playing a completely different game than if you have twelve months.
If you are thinking about taking 2027 off, we need to know whether your cash, severance, and benefits can actually support that decision before we start making big moves with your META stock.
Cash runway means how long you can live without needing another paycheck.
That number should come before the stock decision.
Your Severance Is a Bridge, Not a Bonus
Think of your severance as a bridge, not a bonus.
If your package follows the reported U.S. structure, it may include 16 weeks of base pay plus two additional weeks for every year of service.
That may sound strong on paper.
And in many cases, it is meaningful support.
But here is the part I would want you to slow down and think through:
Your severance may be based on base pay, not your full total compensation.
If your lifestyle was built around base pay, bonus, RSUs, refreshers, and other compensation, then base-pay severance may not replace your real monthly financial life the way you initially think.
That is not a reason to panic.
It is a reason to map it.
If you receive three months, six months, nine months, or more of severance, one way to think about it is:
“I am financially covered for this period, so how do I use this time wisely?”
That does not mean spending like nothing changed.
It means using the cushion to avoid panic.
Maybe it gives you time to decide whether you want another big tech job.
Maybe it gives you time to start something.
Maybe it gives you time to be home with family.
Maybe it gives you time to reset.
But if you do not have a plan for that severance, it can disappear quickly.
And if it disappears quickly, you may end up selling assets prematurely, taking on debt, or making decisions from stress.
That is exactly what we are trying to avoid.
The COBRA Detail Could Change the Entire Runway Math
Health insurance is usually one of the biggest post-layoff expenses.
But if your package includes extended employer-paid COBRA coverage, that can change the equation dramatically.
If you have 18 months of covered COBRA, for example, that may reduce one of the biggest monthly expenses you would otherwise need to fund out of pocket.
That matters.
Because lower monthly burn means your severance and cash may stretch further.
It may give you more room to avoid selling stock in a rushed way.
It may make a partial or full 2027 career pause more realistic.
It may create time to model whether a lower-income year could be used to diversify a concentrated META position more thoughtfully.
But do not assume anything.
Read the actual severance agreement.
Confirm what is covered, who is covered, how long it lasts, what happens if you start a new job, and whether there are deadlines or forms you need to complete.
The COBRA detail is not just a benefits footnote.
It could be the difference between needing to sell stock now and having enough runway to be more strategic.
The META Stock Question Is Really a Concentrated Equity Position Question
You may still believe in Meta.
You may still believe in Mark’s vision.
You may still respect the business.
You may still feel proud of the work you did there.
But there is a massive difference between believing in the company and having your financial life concentrated in it.
A concentrated equity position means a large part of your financial life is tied to one stock.
That matters even more after a layoff.
Your income was already tied to Meta.
Your benefits were tied to Meta.
Your equity was tied to Meta.
Now that the job is gone, your wealth may still be heavily tied to META stock.
That does not mean the stock is bad.
It means the position needs context.
| Planning Area | Question to Ask | Why It Matters |
|---|---|---|
| Liquidity | How much money do you need to safely get through the transition? | Money needed soon should not depend entirely on the price of one stock. |
| Severance | Is your severance based on base pay or total compensation? | Base-pay severance may not fully replace your real lifestyle if RSUs and bonuses were a major part of your compensation. |
| Health insurance | Do you have covered COBRA, and for how long? | Covered healthcare may significantly reduce monthly burn and extend runway. |
| Concentration | How much of your net worth is tied to META? | A large single-stock position may create more risk than you realize. |
| Taxes | Which shares have gains, losses, short-term treatment, or long-term treatment? | The timing and tax lots may affect the after-tax result of any sale. |
| 2027 planning | Could 2027 be a blank-slate planning year? | A lower-income year may create room to evaluate strategic diversification, Roth conversions, or capital gains planning. |
Run a Portfolio X-Ray on the Concentrated META Position
Once liquidity is clear, the next step is understanding the concentrated equity position.
Before the layoff, checking your equity may have been part of the rhythm.
You may have watched internal dashboards, grant cycles, refreshers, vesting dates, and the stock price.
Then the layoff happens, and suddenly the dashboard feels frozen.
The stock is still there.
But the paycheck attached to the company is not.
That is psychologically weird.
It is also financially important.
A Portfolio X-Ray should help answer questions like:
- What percentage of your investable net worth is in META?
- What percentage of your taxable portfolio is in META?
- How much of that position came from vested RSUs?
- How much of it has gains?
- How much has losses?
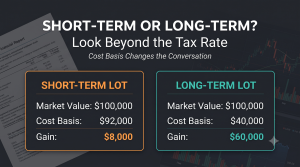
- Which lots are short-term?
- Which lots are long-term?
- How much would you buy today if the same amount were sitting in cash?
- Would your plan still work if the stock dropped?
- Are you holding because it fits your plan, or because you never made a decision after the RSUs vested?
That last question matters.
A lot of people do not intentionally become concentrated in company stock.
It just happens.
RSUs vest.
You hold the shares.
More RSUs vest.
The stock appreciates.
You keep working.
You keep accumulating.
Then one day, you look up and a meaningful part of your net worth is tied to one company.
While you are still employed, that may feel normal.
After a layoff, it deserves a fresh look.
Once RSUs Vest, They Are Part of Your Net Worth
One thing I wish more tech employees understood is that once RSUs vest, they are no longer just some bonus sitting off to the side.
They are part of your net worth.
In many cases, RSUs are taxed as compensation when they vest. After that, if you continue holding the shares, you are making an investment decision.
A simple way to think about it is:
If Meta had paid you the same amount in cash instead of stock, would you turn around today and buy that much META stock?
If the answer is yes, then at least you know you are making an intentional decision.
If the answer is no, then the position may be more accidental than intentional.
That does not mean you have to sell everything.
It means you need a plan.
Your RSUs need a job.
- Some may be safety money.
- Some may be long-term investment money.
- Some may be used to fund a transition.
- Some may be sold over time as part of a diversification plan.
- Some may be held because, after reviewing your full financial picture, you are comfortable with the risk.
But the key is that the decision should be intentional.
Do Not Let Emotion Decide the Stock Plan
Getting laid off can make you want to act quickly.
Sometimes the emotion sounds like:
“I am angry, so I want to sell everything.”
Other times it sounds like:
“I still believe in the company, so I do not want to sell anything.”
Both reactions are understandable.
Neither one is a plan.
I would not want you to sell META stock just because you are angry, scared, or hurt.
I also would not want you to hold META stock only because you feel emotionally attached to the company.
The better question is:
Does this position still fit your life?
Because your life may have changed.
Your income changed.
Your benefits changed.
Your timeline changed.
Your tax picture may change.
Your need for flexibility may change.
So the stock decision should be made in the context of the new plan, not the old one.
If 2026 Is the Severance Year, 2027 May Be the Blank-Slate Year
This is one of the biggest reasons I think this topic is worth writing about.
When you are trapped in high tech tax brackets for years, you usually do not get many low-income years.
You have salary.
You have bonus.
You have RSU income.
You may have refreshers vesting.
You may have investment income.
That is a good problem to have.
But it can also limit certain planning opportunities.
Now imagine you are laid off in 2026.
That year may include:
- Salary
- Bonus
- RSU income
- PTO payout
- Severance
- Possibly stock sales
- Possibly spouse income
So 2026 may still be a high-income year.
But 2027 could look very different.
Maybe you take time off.
Maybe you consult lightly.
Maybe you start a business.
Maybe you travel.
Maybe you spend more time with family.
Maybe you take a year to figure out what is next.
If 2027 has little or no W-2 income, that may change the planning conversation.
A blank-slate 2027 may become a rare, strategic sandbox to evaluate your equity more thoughtfully.
Not a loophole.
Not a guarantee.
Not a reason to avoid work just for taxes.
But potentially a year where your income is low enough to model things that may not have made sense while you were earning full tech compensation.
A lower-income year may create room to evaluate:
- Selling appreciated META shares
- Harvesting capital gains
- Harvesting losses
- Completing a Roth conversion
- Diversifying a concentrated stock position
- Coordinating income with health insurance subsidies if applicable
- Rebuilding the portfolio around the next chapter
The important word is may.
This is not automatic.
It needs to be modeled.
You have to look at federal taxes, state taxes, capital gains, health insurance, household income, deductions, and future plans.
But the concept matters.
If 2026 is the year severance hits, 2027 may be the year to make more thoughtful planning decisions.
The tax system is based heavily on income.
So if your income changes, your planning opportunities may change too.
A Lower-Income Year Does Not Matter If Cash Flow Is Not Protected
This is the part you cannot skip.
A lower-income year can be valuable only if cash flow is protected.
If you do not have enough cash, severance, or safe assets to live on, then you may be forced to sell investments at a time that is not ideal for you.
That is why liquidity comes first.
It is one thing to say:
“I am going to take 2027 off and be strategic.”
It is another thing to actually have the cash, insurance plan, tax reserve, and spending plan to make that possible.
So before we romanticize taking time off, I would want to know:
- How much does your life cost?
- How much cash do you have?
- How much severance will remain after tax?
- Is your COBRA actually covered, and for how long?
- How much income might you have in 2027?
- What happens if your next job takes longer than expected?
- What happens if markets are down?
- What happens if an unexpected expense hits?
This is why the Liquidity Transition Framework and Portfolio X-Ray work together.
The Liquidity Transition Framework helps answer:
Can I afford the transition?
The Portfolio X-Ray helps answer:
How much concentrated META risk can I afford to keep during the transition?
Together, they turn the question from:
“Should I sell META?”
Into:
“How much META can I afford to keep, and what role should it play in the next chapter of my life?”
Could This Layoff Be a Life Planning Moment Too?
I do not want to make layoffs sound easy.
They are not.
Getting let go from a company you worked hard for can feel awful.
It can affect your confidence.
It can affect your identity.
It can make you question what comes next.
But I also think there is another side to the conversation.
If you worked in tech, especially at a company like Meta, you may have been working extremely hard for years.
You may have been compensated well for that work.
Your skill set may have grown.
Your net worth may have grown.
Your options may have grown.
So maybe this is not only a financial transition.
Maybe it is also a chance to take a step back and ask:
- Who am I outside of this company?
- What do I want the next chapter to look like?
- Do I want to jump right back into another high-income W-2 role?
- Do I want to build something on my own?
- Do I want to spend time with family?
- Do I want to take a breath before making the next major career decision?
Again, this only works if the financial side is organized.
But if the cash flow works, the tax planning works, and the investment risk is understood, then a career pause may be more than just time away from work.
It may be a reset.
A Simple Order of Operations After a Meta Layoff
If you came to me with this situation, I would not start by asking whether you think META is going up or down.
I would start here.
| Step | Action | Purpose |
|---|---|---|
| 1 | Calculate monthly spending | Know what life actually costs without a paycheck. |
| 2 | Estimate after-tax severance | Understand the real amount available to fund the transition. |
| 3 | Compare severance to total compensation | Base-pay severance may not replace your full tech compensation lifestyle. |
| 4 | Confirm COBRA and healthcare details | Covered healthcare may materially extend your runway. |
| 5 | Build a tax reserve | Avoid assuming withholding will perfectly match the final tax bill. |
| 6 | Organize META shares by tax lot | Review vesting dates, basis, gains, losses, and holding periods. |
| 7 | Separate safety money from growth money | Decide which dollars need to be protected and which can stay invested. |
| 8 | Use the Liquidity Transition Framework | Map runway before making a major stock decision. |
| 9 | Run a Portfolio X-Ray | Understand how much risk is concentrated in META. |
| 10 | Model 2026 versus 2027 | Compare the severance year with a possible lower-income planning year. |
| 11 | Create a written plan | Avoid making decisions one emotional trade at a time. |
A Better Question for You to Ask
You may be asking:
What should I do with my META stock?
A better question may be:
How much liquidity do I need for this transition, and how much concentrated META risk can my plan actually support?
That shift matters.
Because the goal is not to predict META stock.
The goal is to make sure every dollar has the right job.
Cash has a job.
Severance has a job.
RSUs have a job.
META stock has a job.
Your tax plan has a job.
Your health insurance plan has a job.
And your next year has a job too.
If you were recently laid off from Meta and are considering taking part or all of 2027 off, I would not rush the stock decision.
I would first ask:
How much liquidity do you need for this transition?
And then:
How much concentrated equity risk can your plan actually support?
That is the real conversation.
Request the Liquidity Transition Framework
If you were laid off from Meta and are trying to coordinate severance, RSUs, cash flow, taxes, health insurance, and a concentrated META position, start with liquidity.
The Liquidity Transition Framework can help you organize the transition before making major decisions with company stock.
Request the FrameworkMeta Layoff, RSU, and Severance Planning Frequently Asked Questions
Should I sell my META stock after being laid off from Meta?
There is no universal answer. The decision may depend on your cash runway, severance, taxes, health insurance, concentration risk, holding periods, cost basis, and long-term financial plan. This article is not a recommendation to buy, sell, or hold META stock.
Why does a concentrated META stock position matter after a layoff?
A concentrated equity position means a meaningful part of your financial life may depend on one company’s stock. After a layoff, that concentration deserves fresh review because your income and benefits may have already been affected by the same company.
Why might 2027 matter if I was laid off in 2026?
If 2026 includes salary, bonus, RSU income, PTO payout, and severance, it may still be a high-income year. If 2027 has little or no W-2 income, it may create planning opportunities that should be modeled carefully with qualified professionals.
Why does base-pay severance matter?
If your severance is calculated from base pay, it may not fully replace your actual total compensation if RSUs, bonuses, or other equity compensation were a major part of your income. That is why the severance number should be compared to your real monthly expenses and total compensation history.
Why does COBRA coverage matter?
Healthcare can be one of the largest post-layoff expenses. If your package includes covered COBRA for a period of time, that may lower your monthly burn rate and extend your runway. You should confirm the exact terms in your own severance and benefits documents.
What is the Liquidity Transition Framework?
The Liquidity Transition Framework is designed to help organize cash, severance, taxes, health insurance, expenses, and equity during a major transition. It is educational and does not provide personalized investment, tax, or legal advice.
What is a Portfolio X-Ray?
A Portfolio X-Ray is a review of how your investments are positioned, including whether too much of your net worth or taxable portfolio is concentrated in one company. For a former Meta employee, this may include reviewing META stock exposure, tax lots, gains, losses, and how the position fits the broader plan.
Important Information
369 Financial is a registered investment adviser. This content is for informational and educational purposes only and does not constitute personalized investment advice, tax advice, legal advice, or a recommendation to buy, sell, or hold any security.
All opinions expressed are solely those of the author and do not reflect the views of any affiliated institutions. Past performance is not indicative of future results. All investing involves risk, including the potential loss of principal.
Information about severance, COBRA, benefits, and equity compensation may vary by employee, location, role, agreement, and employer policy. You should review your own plan documents, severance agreement, equity award agreements, and benefits materials before making decisions.
Please consult a qualified financial, tax, and legal professional before making any decisions based on your individual circumstances.
369 Financial is not affiliated with Meta Platforms, Inc. or any of its subsidiaries.